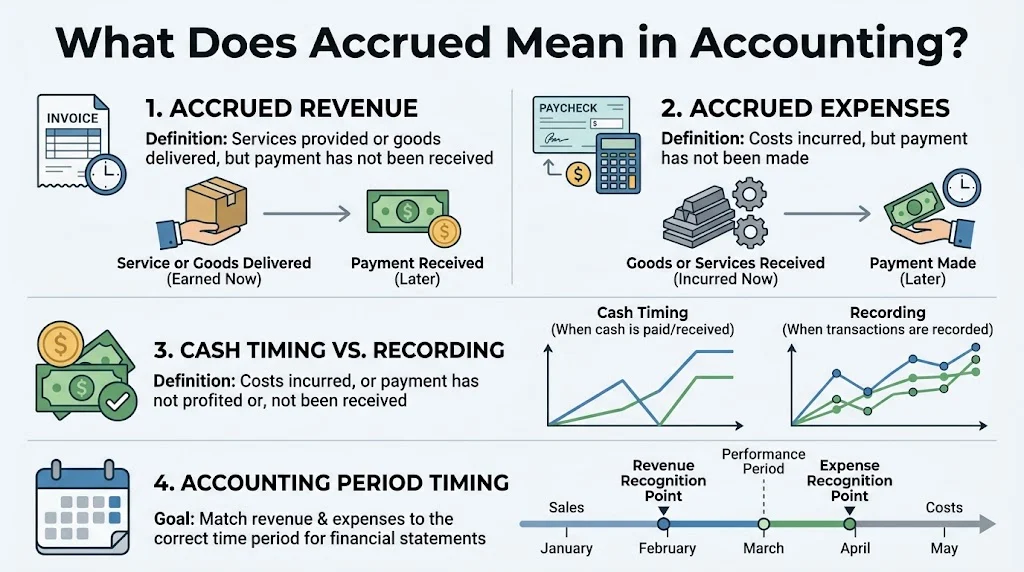
What does accrued mean in accounting? It means recording revenue or expenses when they are earned or incurred, even if cash has not yet been received or paid. Accrual accounting therefore matches financial activity with the period it belongs to.
What does accrued mean in accounting? It means that a company recognizes an economic event before the related cash transaction happens. This concept sits at the heart of accrual accounting.
For example, a business may provide services in December but receive payment in January. The business earned revenue in December. Therefore, it records the revenue in December rather than waiting for January’s cash receipt.
The same idea applies to expenses. A company may receive electricity service during March and pay the bill in April. The expense belongs to March because that is when the company used the service.
As a result, accrual accounting gives financial statements a more accurate picture of business activity during a specific reporting period.
This guide explains the meaning of accrued amounts in plain US English. It also covers accrued revenue, accrued expenses, journal entries, financial statements, practical examples, common misunderstandings, and frequently asked questions.
Quick Answer Box
| Meaning | Context | Primary Platforms | Example | Tone |
| Recognized before cash moves | Accrual accounting | General accounting, bookkeeping, financial reporting | Salary earned in June but paid in July | Professional |
| Revenue earned but not yet collected | Accrued revenue | Income statements and balance sheets | Service completed before customer payment | Formal |
| Expense incurred but not yet paid | Accrued expense | Financial statements and bookkeeping | Utilities used before the bill is paid | Formal |
| A timing concept | Accounting periods | Business accounting systems | Interest accumulated before payment | Technical |
What Does Accrued Mean in Accounting?
What does accrued mean in accounting? In simple terms, accrued describes income or expenses that accounting records recognize before the related cash changes hands.
The word comes from the idea of something accumulating over time. In accounting, an amount can build up even though payment has not happened yet.
For example, imagine a company earns $5,000 from consulting work in December. The client agrees to pay in January. The company still earned $5,000 in December.
Under accrual accounting, the company records the revenue in December.
The company does not wait for the bank deposit.
That distinction matters because accounting focuses on when economic activity occurs. Cash flow focuses on when money actually moves.
Accrual Versus Cash Accounting
Cash accounting records transactions when cash changes hands. Accrual accounting records qualifying revenue when it is earned and expenses when they are incurred.
Consider a company that completes a $3,000 project on December 20. The client pays on January 10.
Under cash accounting, the transaction may appear in January.
Under accrual accounting, the revenue belongs to December.
This difference can significantly affect monthly, quarterly, and annual financial reports.
| Feature | Accrual Accounting | Cash Accounting |
| Revenue timing | When earned | When cash is received |
| Expense timing | When incurred | When cash is paid |
| Accounts receivable | Common | Generally not used in the same way |
| Accrued expenses | Common | Usually not recorded before payment |
| Financial reporting | Provides period matching | Emphasizes cash movement |
Accrued Revenue
Accrued revenue represents income a business has earned but has not yet collected.
Suppose a consulting firm completes work worth $8,000 in September. The customer will pay in October.
The firm may recognize $8,000 of revenue in September. It also records an asset, often called accrued revenue or a receivable, depending on the circumstances and accounting policy.
The basic idea is simple:
The company earned the money, but it has not collected the money yet.
Common examples include:
- Consulting services already delivered
- Interest earned but not yet received
- Rent earned but not yet collected
- Contract work completed before billing
- Certain professional services performed before invoicing
Accrued Expenses
An accrued expense represents a cost the business has incurred but has not yet paid.
For instance, employees may work during the final week of December. The company pays those employees in January.
The December financial statements should generally recognize the payroll expense associated with December work.
The company therefore records an expense and a related liability.
Common examples include:
- Employee wages
- Interest expense
- Utilities
- Taxes
- Professional fees
- Bonuses
- Repairs or services received but not yet billed
Why Accruals Matter
Accruals help companies match financial activity with the period in which it occurs.
Without accruals, monthly results can become distorted.
Imagine a company receives a large annual insurance bill in January. If the entire cost appears in January, that month may show an unusually large expense. Other months may show artificially low expenses.
Accrual and related adjusting processes help financial reporting reflect the underlying economic activity more appropriately.
Contextual Dynamics and Nuances of the Term
The meaning becomes clearer when you understand the timing behind the transaction.
An accrued amount generally involves three separate events:
- The business activity happens.
- Accounting recognizes the activity.
- Cash moves later.
However, the exact accounting treatment depends on the transaction.
Earned Versus Received
Revenue can be earned before it is received.
For example, a company performs a service today. The customer agrees to pay next month.
The service has already created revenue under the applicable revenue recognition rules. The later payment simply settles the related receivable or accrued balance.
Therefore, earned and received do not necessarily mean the same thing.
Incurred Versus Paid
Expenses work in a similar way.
A business can incur an expense before paying it.
Suppose an employee works during December. The payroll department processes payment in January.
The labor cost relates to December.
Consequently, the business recognizes the applicable expense in December and records a liability until payment occurs.
Accrued Does Not Mean Paid
This distinction causes many beginner errors.
An accrued expense is not the same as a paid expense.
|
Situation |
What Happened? |
|
Accrued expense |
Expense happened, payment has not occurred |
|
Paid expense |
Cash has been paid |
|
Accrued revenue |
Revenue has been earned, cash has not been received |
|
Collected revenue |
Cash has been received |
Accrued Does Not Always Mean Unbilled
People sometimes use the terms interchangeably. They are not always identical.
An amount can be earned before invoicing. However, accounting treatment depends on the specific transaction and applicable reporting rules.
For example, a company may have completed work but not yet issued an invoice. The accounting system may recognize revenue through an accrual or another receivable mechanism.
The underlying principle remains the same: timing matters.
Accruals and the Matching Concept
The matching concept helps explain why accrued expenses exist.
Businesses generally recognize expenses in the periods associated with the revenue or economic activity they help generate.
For example, employees work in December. Their labor supports December operations. Therefore, the related payroll cost belongs to December even when payment happens in January.
This approach creates more meaningful financial statements.
Real Life Conversation Examples Using What Does Accrued Mean in Accounting
The phrase what does accrued mean in accounting often appears in beginner accounting questions. However, real conversations usually use simpler wording.
Here are five practical scenarios.
Conversation 1: Accrued Expense
Alex: I keep seeing accrued expenses on the balance sheet. What are they?
Jordan: They are expenses the company has already incurred but has not paid yet.
Alex: So the cash has not left the business?
Jordan: Exactly. For example, employees may earn wages in December, but the company pays them in January.
Alex: So December still gets the expense?
Jordan: Yes, because the employees performed the work in December.
Conversation 2: Accrued Revenue
Mia: What does accrued mean in accounting when we talk about revenue?
Sam: It usually means the company has earned revenue but has not collected the cash yet.
Mia: Can you give me an example?
Sam: Sure. Suppose we finish a $4,000 consulting project in May and receive payment in June.
Mia: Then the revenue belongs to May?
Sam: Correct, assuming the revenue recognition requirements are satisfied.
Conversation 3: Payroll
Employee: Why does accounting record payroll before payday?
Accountant: Because employees earn wages as they work.
Employee: So if I work during the last week of December, that cost belongs to December?
Accountant: Yes. Payment may occur in January, but the expense relates to the December work.
Conversation 4: Interest
Manager: Why did we record interest expense before paying the loan?
Accountant: Interest can accumulate over time.
Manager: So we owe it even though the bank has not received the payment?
Accountant: Correct. The company recognizes the applicable interest expense and liability as it accrues.
Conversation 5: Month End
Bookkeeper: Why are we posting an adjusting entry at month end?
Controller: We received services this month, but the vendor has not sent the invoice yet.
Bookkeeper: So we still need to record the expense?
Controller: Yes. The cost belongs to this reporting period.
Bookkeeper: Then we can adjust the liability when the invoice arrives?
Controller: Exactly.
These conversations show why the phrase can sound complicated even though the underlying idea is straightforward.
Platform Specific Breakdown
Accounting terminology does not function like social media slang. Therefore, the phrase appears differently across digital platforms.
Search engines, accounting software, educational websites, forums, and social media may all use slightly different language.
The accounting meaning stays consistent. However, the surrounding wording changes.
How It Is Used on Snapchat
Snapchat is not an accounting platform. Therefore, people rarely use the phrase as specialized accounting terminology there.
A student might send a message such as:
“What does accrued mean in accounting? I have a quiz tomorrow.”
A friend might answer:
“It means the income or expense is recorded when it happens, not necessarily when cash moves.”
The platform affects the tone, not the accounting principle.
The Role of What Does Accrued Mean in Accounting on TikTok
TikTok often turns technical subjects into short educational explanations.
Creators may explain accruals using everyday examples.
For example, a video might compare a paycheck with the days an employee actually worked. Another video might compare a restaurant receiving a bill with the month when the restaurant used the service.
Short videos can make the concept easier to remember.
However, viewers should still check technical claims against reliable accounting guidance. Simplified content can omit important details.
Instagram and Texting Dynamics
Instagram captions often favor short explanations.
A finance creator might write:
“Accrued expense = incurred now, paid later.”
That summary can work as a beginner’s explanation.
Text messages can be even shorter:
“Accrued means recorded now, cash later.”
However, the phrase should not replace the underlying accounting distinction.
A professional accountant may need to explain the specific transaction, recognition requirements, account classification, and adjusting entry.
Alternative Meanings and NLP Variations of the Phrase
The word accrued has a stable accounting meaning, but writers use several related terms.
Understanding these variations improves search visibility and comprehension.
Common Semantic Variations
| Phrase | Meaning |
| Accrued expense | Cost incurred but not yet paid |
| Accrued revenue | Revenue earned but not yet collected |
| Accrued income | Income earned but not yet received |
| Accrued interest | Interest accumulated over time |
| Accrued wages | Employee compensation earned but not yet paid |
| Accrued liabilities | Obligations recognized before payment |
| Accrual | Accounting adjustment recognizing an earned or incurred amount |
| Accrual basis | Accounting method that recognizes qualifying activity based on economic events |
Natural Language Variations
People may search for the same concept using different wording.
Common searches include:
- What does accrued mean in accounting?
- What is an accrued expense?
- What does accrued revenue mean?
- What does accrual mean?
- What does accrued mean on a balance sheet?
- Is accrued the same as unpaid?
- What is the difference between accrued and deferred?
- When do you record accrued expenses?
- Why are accruals used?
- How do accrual journal entries work?
These variations represent closely connected search intent.
Accrued Versus Deferred
Accrued and deferred describe different timing situations.
An accrual generally recognizes an amount before the related cash transaction occurs.
A deferral generally delays recognition because the accounting recognition event has not yet occurred.
For example, a company may receive cash before providing a service. That situation can create deferred revenue or contract liability.
By contrast, a company may provide the service before receiving cash. That situation can create accrued or receivable revenue.
| Situation | Typical Timing |
| Accrued revenue | Earned before cash receipt |
| Deferred revenue | Cash received before revenue is earned |
| Accrued expense | Expense incurred before payment |
| Prepaid expense | Cash paid before expense recognition |
The distinction is essential for accurate financial reporting.
Misinterpretations: When NOT to Use What Does Accrued Mean in Accounting
The question what does accrued mean in accounting is useful when someone needs a definition. It is not always the best wording for every accounting situation.
Avoid using the term as a universal synonym for “unpaid.”
An unpaid invoice may represent a normal accounts payable balance. It does not automatically mean the transaction is an accrued expense.
Likewise, an amount shown as a receivable does not automatically require the label “accrued revenue.”
Do Not Confuse Accrued With Deferred
These concepts move in different directions.
Accrued amounts recognize economic activity that has already occurred.
Deferred amounts postpone recognition because the relevant activity has not yet been recognized.
Using the wrong term can create confusion in financial reports.
Do Not Assume Every Accrual Is a Cash Problem
Accrual accounting concerns recognition and timing.
Cash management concerns liquidity.
A profitable company can have cash flow problems. Similarly, a company can have strong cash flow during a period without generating equivalent accounting profit.
Therefore, accrual accounting and cash management answer different questions.
Do Not Treat Every Accrued Amount as Identical
The account classification matters.
For example, accrued payroll, accrued interest, accrued taxes, and accrued revenue can affect different accounts and financial statement sections.
The exact journal entry depends on the transaction.
How to Respond in Chat Comfortably
If someone asks, what does accrued mean in accounting, you do not need a long textbook explanation.
A simple response works well:
“It means the income or expense is recorded when it is earned or incurred, even if the cash comes later.”
For an even shorter response, say:
“Accrued means it has happened for accounting purposes, but the cash has not moved yet.”
For a business context, you can add an example:
“For example, employees can earn December wages that the company pays in January. The wages are accrued in December.”
Professional Response
“An accrued amount is recognized in the accounting period when the related revenue is earned or expense is incurred, even though payment or collection occurs later.”
Beginner Friendly Response
“It means the business records something now because it has already happened, even though the money comes later.”
Text Message Response
“Accrued = recorded now, cash later.”
Each response fits a different audience.
FAQs
1. What does accrued mean in accounting?
What does accrued mean in accounting? It means recognizing qualifying revenue or expenses in the period when they are earned or incurred, even if cash changes hands later.
2. Is accrued the same as unpaid?
Not always.
An accrued expense is generally an expense that has been incurred but not yet paid. However, not every unpaid amount should automatically be classified as an accrued expense.
3. What is an accrued expense?
An accrued expense is a cost a company has incurred but has not yet paid.
Common examples include payroll, interest, utilities, taxes, and professional services.
4. What is accrued revenue?
Accrued revenue is revenue a business has earned but has not yet collected.
For example, a company may complete consulting work in June and receive payment in July.
5. What does accrued mean on a balance sheet?
An accrued amount can appear through an asset or liability, depending on the transaction.
Accrued expenses generally create liabilities. Accrued revenue can create an asset or receivable.
The exact presentation depends on the transaction and applicable accounting framework.
6. Why do businesses record accruals?
Businesses record accruals to reflect economic activity in the appropriate reporting period.
This helps financial statements provide a more meaningful view of performance and obligations.
7. What is an example of an accrued expense?
Suppose employees earn $20,000 during the final week of December. The company pays those wages in January.
The company generally records the applicable December payroll expense and related liability before payment.
8. Is accrued revenue an asset?
Accrued revenue can result in an asset because the company has a right to receive consideration for goods or services already provided.
The exact account classification depends on the facts and applicable accounting requirements.
9. What is the difference between accrued and deferred?
Accrued items generally involve recognizing an amount because the underlying activity has occurred.
Deferred items generally postpone recognition because the related revenue or expense has not yet met the applicable recognition conditions.
10. Does accrued mean the company has cash?
No.
An accrued amount does not necessarily mean cash has been received or paid.
That is one of the most important distinctions in accrual accounting
Conclusion
The phrase what does accrued mean in accounting reflects a common beginner question rather than internet slang.
The underlying concept is fundamental to financial reporting.
Accrued means that an economic event has been recognized even though the related cash movement has not necessarily happened.
Revenue can be earned before collection.
Expenses can be incurred before payment.
That timing difference explains many of the entries found in accrual based financial statements.
For example, a business can complete work in December and collect the money in January. The revenue may belong to December.
Likewise, employees can work in December and receive their wages in January. The applicable payroll expense still relates to December.
The key lesson is simple: accounting timing and cash timing are not always the same.
Once that distinction becomes clear, accrued revenue, accrued expenses, accrued interest, payroll accruals, and similar concepts become much easier to understand.
When someone asks what does accrued mean in accounting, the clearest answer is usually this:
It means the accounting records recognize an amount because the underlying economic activity has occurred, even though the related cash may be received or paid later.
That principle helps businesses report financial activity in the period to which it belongs. It also gives managers, investors, accountants, and other users a clearer picture of financial performance and obligations.
